Homebuying Process 2025: Step-by-Step Guide to Buying a House
Written by Graham Team · Graham Team Real Estate Advisors — Henderson & Las Vegas, NV · Contact
Master the 2025 homebuying process with our step-by-step guide. Avoid costly mistakes, secure the right mortgage, and buy your dream house with…
Dated: August 25 2025
The 2025 Guide to Buying a Home: Step-by-Step Process Explained
Buying a home isn’t just a financial decision — it’s a journey that mixes strategy, patience, and paperwork with the thrill of getting your own keys. And in today’s real estate market, knowing the process upfront can help you avoid costly mistakes and feel confident in every move you make.
Whether you’re a first-time buyer or purchasing your second (or third) property, here’s the updated step-by-step guide to buying a house in 2025.
Step 1: Get Pre-Approved for a Mortgage
Before you scroll through Zillow or tour open houses, your first stop is with a lender. A mortgage pre-approval tells you how much home you can afford and signals to sellers that you’re a serious buyer.
Think of it like car shopping: you don’t want to be test-driving Bentleys when your budget fits a Honda. Pre-approval sets realistic expectations and ensures your offer stands strong when the right home comes along.
TIP: Use an online mortgage calculator to estimate your monthly payments.
(Also check out our post on homebuying assistance if you’re exploring flexible financing options).
Step 2: Start Your Home Search
Once you know your budget, the fun begins. You’ll tour homes, weigh neighborhoods, and decide what features matter most. When you find the one, your agent will help you write and submit an offer.
Negotiation often comes into play here. A skilled team like ours works to position your offer competitively while protecting your interests. Read our 5-star reviews!
Step 3: Open Escrow and Deposit Earnest Money
After your offer is accepted, the escrow process kicks off. Escrow is a neutral third party that holds funds until all conditions of the sale are met. You’ll submit your earnest money deposit (typically 1–3% of the purchase price), showing the seller you’re committed.
Don’t worry, if certain contingencies aren’t met, that money can be refunded.
Step 4: Navigate Contingency Deadlines
This stage is about due diligence:
- Home Inspection (around 10 days): Ensures the home is safe and sound.
- Appraisal: Ordered by your lender to confirm the home’s value supports the loan.
- HOA Rules & Docs: If applicable, you’ll review community restrictions and fees.
Meeting these deadlines protects your deposit and gives you an exit plan if major issues arise.
Step 5: Secure Full Loan Approval
You’re halfway there. Your lender finalizes underwriting, reviews all documents, and issues full loan approval. Staying proactive here (responding quickly to requests for paperwork) helps avoid last-minute delays.
Step 6: Review the Settlement Statement
Next, you’ll receive your closing disclosure or settlement statement. This document itemizes all fees, credits, deposits, and costs of the transaction.
We’ll review it with you line by line so you understand exactly where your money is going.
Step 7: Schedule Your Signing Appointment
When it’s time to sign, you’ll either head to the escrow office or meet with a notary at a location convenient for you. You’ll finalize loan paperwork and escrow documents here. Don't forget to bring your ID!
Step 8: Do the Final Walk-Through
A few days before closing, you’ll check that the home is in the same condition as when you made your offer. Typically, sellers are moved out by now, giving you a chance to spot any issues before closing.
Final Step: Get the Keys to Your New Home
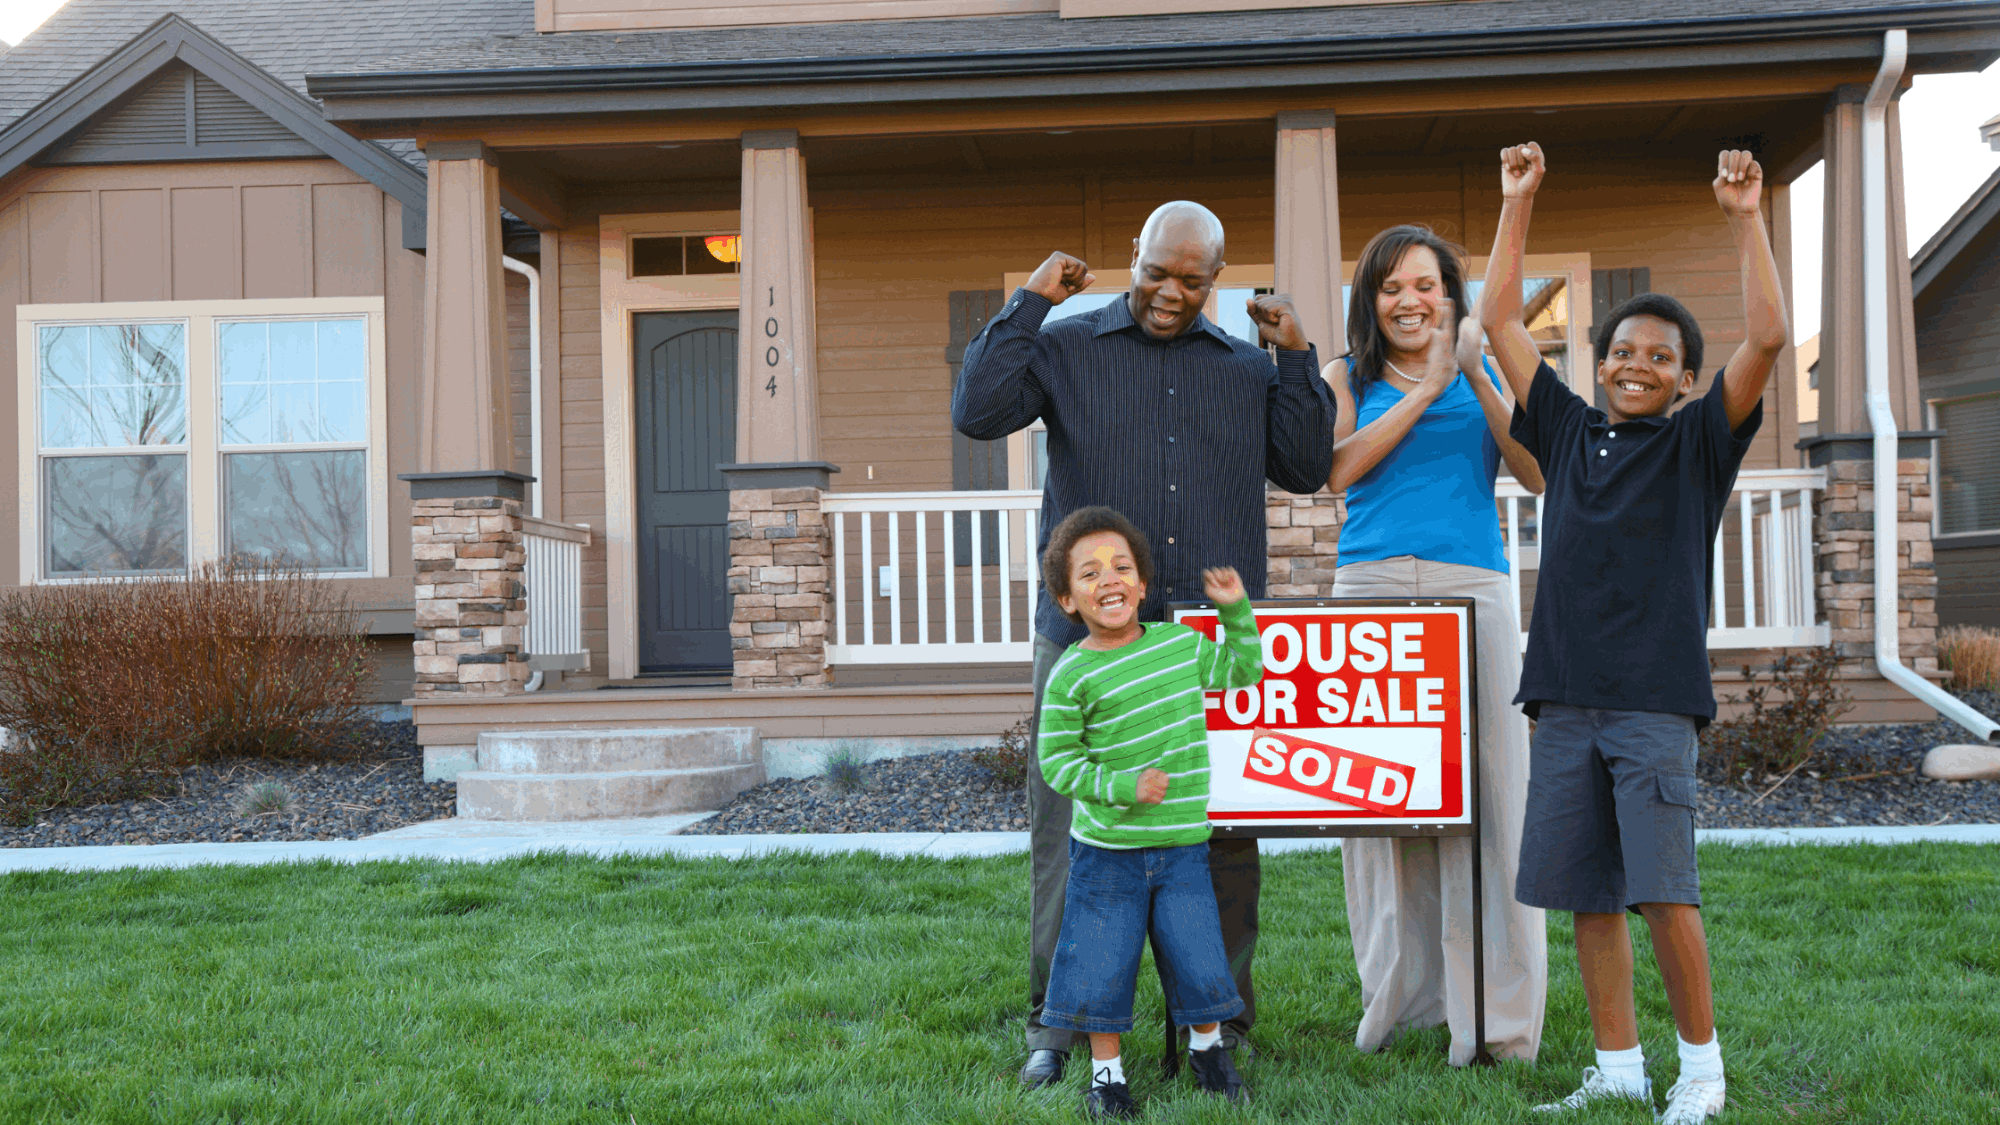
Once the sale records with the county, the home is officially yours. We’ll hand you the keys, and just like that...welcome to homeownership! 🎉
Why This Matters in 2025
With mortgage rates still hovering in the 6% range (see our latest market update), timing and preparation matter more than ever. Having your pre-approval, contingencies, and financials in order can make the difference between winning your dream home or missing out.
If you’re ready to start your home search in Las Vegas or Henderson, connect with us today. We’ll walk you through every step from pre-approval to popping the champagne when you get the keys.
Graham Team Real Estate • (702) 930-9551 • Team@grahamteamnv.com
Instagram | Facebook | YouTube | LinkedIn | TikTok
3007 W Horizon Ridge Pkwy, Ste. 210, Henderson, NV 89052
Frequently asked questions
What is the first step in the 2025 homebuying process?▾
The very first step in the 2025 homebuying process is getting pre-approved for a mortgage. Before touring properties, a lender must verify your financial situation to determine exactly how much you can afford. This prevents you from falling in love with homes out of your budget and proves to sellers that you are a serious, qualified buyer.
How long does the process of buying a house typically take?▾
The average timeline for buying a house ranges from 30 to 45 days once you are under contract. However, the entire homebuying process—including saving for a down payment, finding a lender, searching for properties, and negotiating an offer—often takes three to six months. Market conditions and local inventory levels can also impact this timeline.
What is earnest money, and when is it paid?▾
Earnest money is a good faith deposit, usually 1% to 3% of the purchase price, showing the seller you are committed to buying a house. You will deposit this money into an escrow account shortly after your offer is accepted. In the homebuying process, these funds are held securely and eventually applied to your down payment at closing.
Why is a home inspection critical when buying a house?▾
A home inspection is a critical step in the homebuying process because it uncovers hidden structural, mechanical, or safety issues with the property. Typically conducted within 10 days of contract acceptance, the inspection report gives you the necessary leverage to negotiate repairs, request price reductions, or walk away from the transaction entirely.
Can I buy a home in 2025 without a 20% down payment?▾
Yes, you do not need a 20% down payment to successfully navigate the homebuying process. Many modern loan programs, like FHA loans or conventional conforming loans, allow down payments as low as 3% to 3.5%. First-time buyers may also qualify for state and local assistance programs to make buying a house even more affordable.
What is the difference between mortgage pre-qualification and pre-approval?▾
Pre-qualification is a basic estimate of your borrowing power based on unverified information you self-report. In contrast, pre-approval is a formal commitment where a lender verifies your tax documents, credit history, and employment. Getting pre-approved is a crucial milestone in the homebuying process, signaling to sellers that your financing is secure.